A lemon-law buyback is usually the price you paid plus the charges the state lists, minus a deduction for the miles you drove. That deduction, the “use offset”, is set by each state’s statute, and the states don’t agree. California takes the price times the miles before the first repair visit, divided by 120,000 (Civ. Code 1793.2(d)(2)(C)). New York divides by 100,000 and skips the first 12,000 miles. Pennsylvania caps it at the lesser of 10 cents a mile or 10% of the price. Ohio has no deduction at all. The estimator below, part of our lemon law basics guide, works out the refund items and the offset under the rule in 32 state statutes we read in official text on 11 November 2026, and shows the section with every figure.
This page is general information, not legal advice and not a substitute for the advice of an attorney. Lemon laws, deadlines and required steps vary by state and change. The statute, the maker, a state board or a court decides a claim.
The estimator’s figures are estimates: the maker, a state board or a court decides what is actually paid. It doesn’t say whether a car qualifies under any law; for the repair counts and day limits that come first, use the lemon law checker. For what a repurchase involves from start to finish, title, loan payoff and all, see how a lemon law buyback works.
How the estimator works
It needs three kinds of numbers from your paperwork: what you paid, what else the state counts, and the odometer at the points the state’s formula names. Every entry has a round example figure (a $40,000 car, $3,000 of tax and fees, $1,000 of finance charges, $500 of towing and rental, 6,000 miles at the first repair visit, 15,000 now); replace them with your own.
- State, vehicle type and lease. Only the states in the table further down are listed. A motorcycle or motor home gets a figure only where we read that state’s rule for it (motorcycles: Massachusetts, Oregon, Pennsylvania, Washington; motor homes: Florida, New York, Oregon, Washington). A lease gets a figure only where the offset text names a lease figure. Anything else shows “not confirmed”.
- The refund items. The vehicle price including any trade-in credit, before taxes and fees; then taxes and official fees; finance charges paid; and towing, rental and similar costs caused by the defect. The estimator adds only the items that state’s statute names, and says which it added. New York and Vermont refund the sales or purchase-and-use tax through the state, not the maker; the estimator still counts the taxes you enter there and says so. For a lease, it adds the lease payments you enter instead of the price.
- Three odometer readings. At delivery; at the state’s first point (the first repair visit, first report, first notice or 3rd repair, depending on the state); and now, or at the hearing or the maker’s acceptance of return. The result tells you which miles your state counts, so you know which reading matters.
- Two state-only fields. Oregon takes off 10 miles for each period you didn’t have the car while it was being repaired. Virginia ties its cap to the IRS business mileage rate, so you pick the rate period.
The results: the refund items total and what it includes; the use offset; how to read the offset (a figure from the formula, a ceiling, words only, or zero); the refund items minus the offset; the rule type and the miles the rule counts, in words; the miles and divisor used; and the statute section with its read date.
About miles at delivery. The estimator counts the miles you drove after delivery: each reading minus the odometer at delivery. Many statutes speak of miles “attributable” to the consumer’s use, which fits that. Some speak of miles the vehicle “traveled” before a point (California, Colorado, Massachusetts, Montana, Rhode Island, South Carolina, South Dakota, Vermont), and New Jersey of “the mileage at the time” of the first repair visit, which on its face could include the few miles on the odometer when you took delivery. Set the delivery reading to 0 to see that version. Oregon counts the vehicle’s mileage itself, so the estimator uses the odometer reading there whatever you enter for delivery.
The offset rules, by type
Nine kinds of rule appear in the 32 statutes. The estimator has one branch for each.
| Rule type | Formula | States in the estimator |
|---|---|---|
| Price x miles / divisor | price x miles counted / 120,000 or 100,000 | California, Colorado, Florida, Iowa, Massachusetts, Montana, New Jersey, North Carolina, Rhode Island, South Carolina, South Dakota, Vermont, Washington |
| A ceiling of the same kind | at most price x miles / divisor | Delaware (100,000), Idaho (120,000) |
| Free miles first | (miles – free miles) x price / divisor | New York (12,000 free, / 100,000), Oklahoma (15,000 free, / 120,000) |
| Two parts | price x (miles to first report + miles over 25,000) / 100,000 | Michigan |
| Two rates | total price x miles to first report / 120,000 + half of total price x miles from first report to hearing / 120,000 (total price: the price with taxes and fees, without interest) | Texas |
| Price plus charges | (price + collateral charges) x odometer / divisor | Oregon |
| Cents a mile with a cap | at most 10 cents a mile or 10% of the price, the lesser; DC: at most 10 cents a mile over 12,000; Virginia: at most half the IRS business rate a mile | Minnesota, North Dakota, Pennsylvania; District of Columbia; Virginia |
| Share of the price | at most 15% of the price | Maryland |
| Words only, or none | a “reasonable allowance” with no formula; or no deduction | Arizona, Illinois, Kansas, Missouri, Nebraska (words); Ohio (none) |
Two things the table can’t show. First, a figure from the formula is still an estimate: the price that goes into it, the miles and the extra charges are often what an arbitration or a negotiation is about. Second, several states let the maker also deduct for damage beyond normal wear (Delaware, DC, Maryland, Michigan, New York, Virginia, among those read). The estimator doesn’t, because no formula sets that amount.
Worked examples
This page is general information, not legal advice and not a substitute for the advice of an attorney. Lemon laws, deadlines and required steps vary by state and change. The statute, the maker, a state board or a court decides a claim.
California: the default example
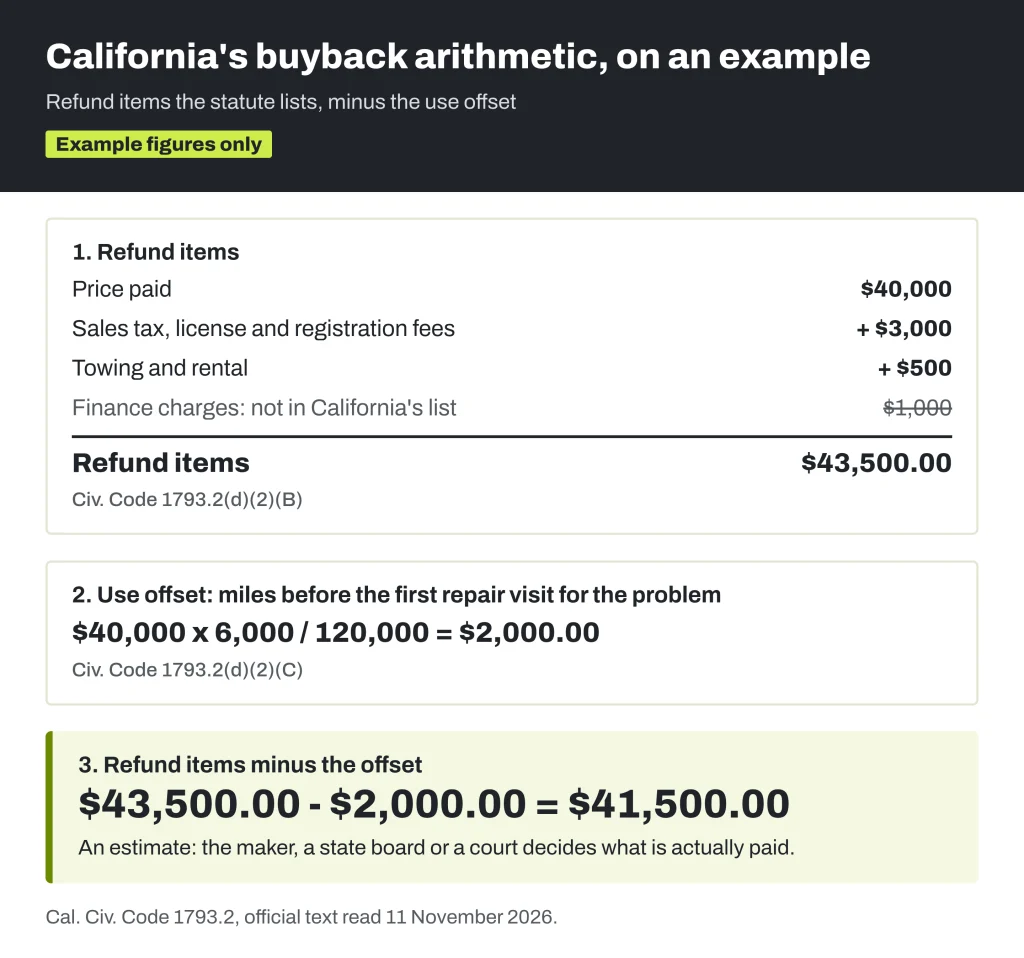
A car bought for $40,000, with $3,000 of sales tax, license and registration fees, $1,000 of finance charges and $500 of towing and rental, first taken in for the defect at 6,000 miles. California’s refund list names the price, the official fees and taxes, and incidental damages, but does not name finance charges (1793.2(d)(2)(B)). The estimator leaves them out; whether finance charges count as part of the price “paid or payable” is for the maker, a board or a court:
- Refund items: $40,000 + $3,000 + $500 = $43,500.00.
- Use offset: $40,000 x 6,000 / 120,000 = $2,000.00 (1793.2(d)(2)(C)).
- Refund items minus the offset: $41,500.00, as an estimate.
For a maker on the opt-in list under CCP 871.20 to 871.30, in a lawsuit under CCP 871.20, CCP 871.27 can change the price paid (maker rebates out) and add offsets for third-party add-ons and negative equity; the estimator doesn’t make those adjustments.
Texas: two rates
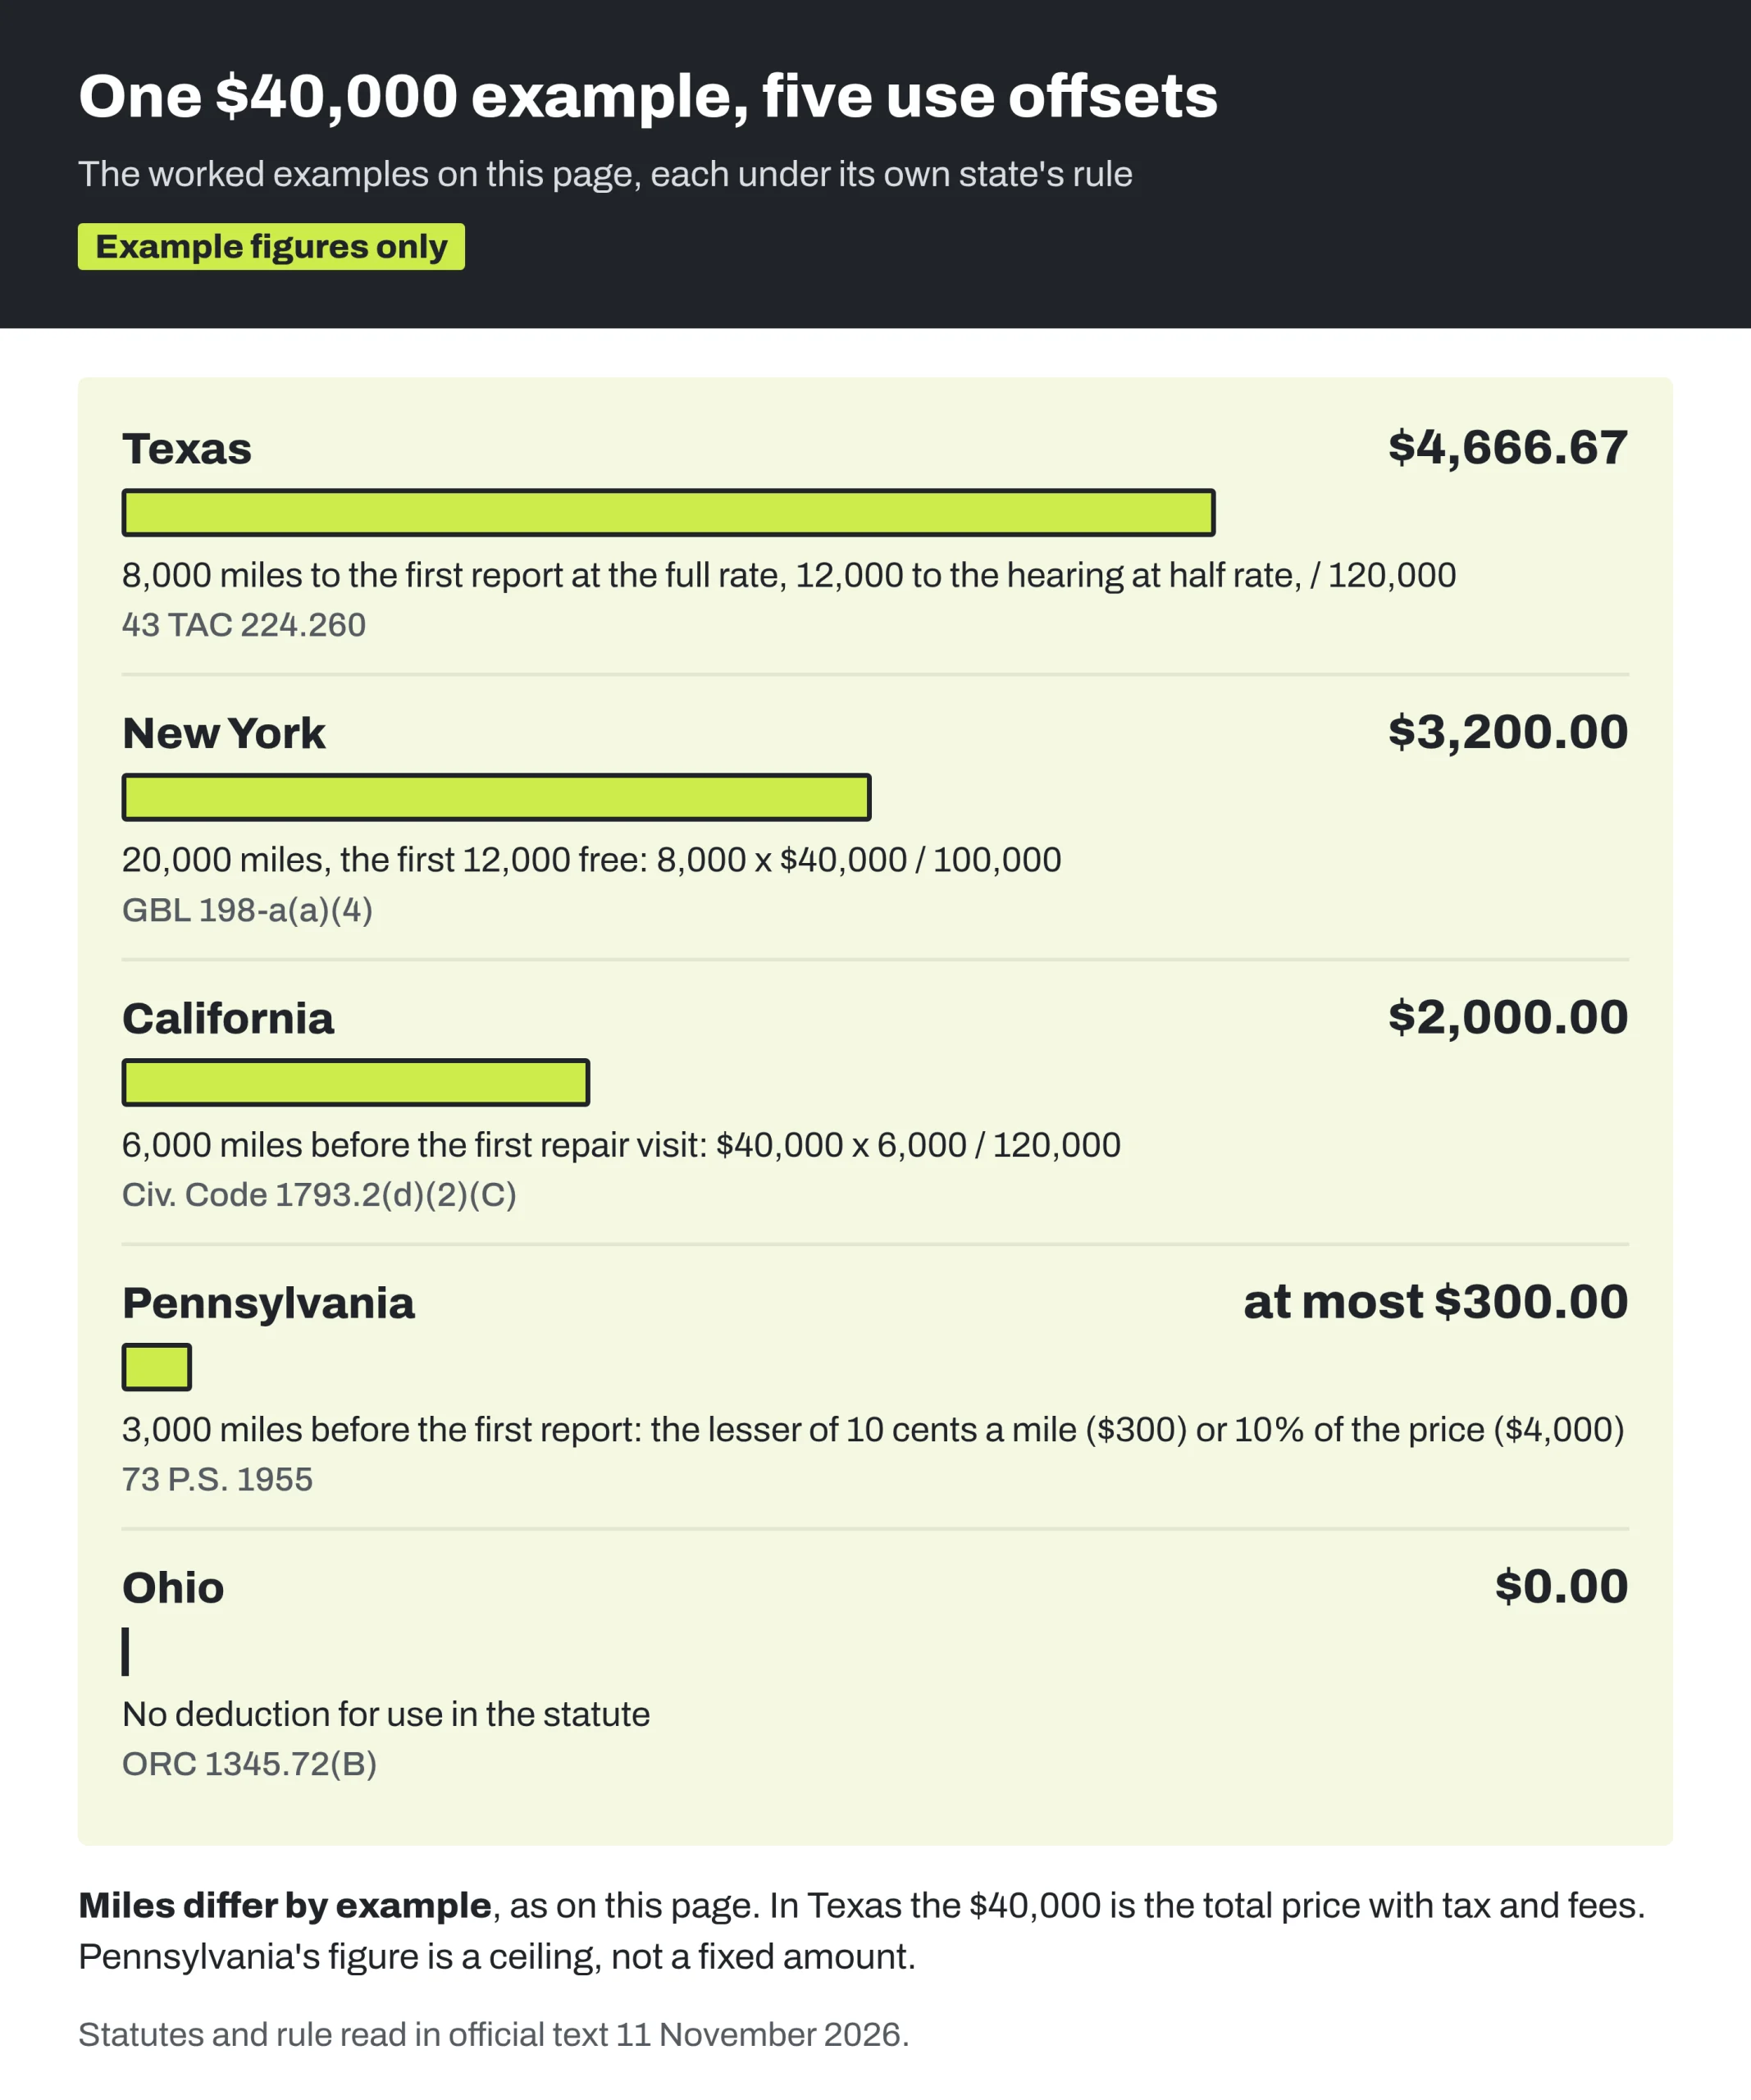
A car with a total purchase price of $40,000 ($37,000 plus $3,000 of tax, title, license and registration; interest and finance charges left out), delivered at 10 miles, first reported at 8,010, with the hearing at 20,010. The rule charges the full rate on miles to the first report and half the rate on miles from the first report to the hearing (43 TAC 224.260):
- $40,000 x 8,000 / 120,000 = $2,666.67
- 0.5 x $40,000 x 12,000 / 120,000 = $2,000.00
- Use offset: $4,666.67.
New York: the first 12,000 miles are free
A $40,000 car with 20,000 miles: (20,000 – 12,000) x $40,000 / 100,000 = $3,200.00 (GBL 198-a(a)(4)). At 10,000 miles the deduction is $0.00, because the formula counts only miles “in excess of twelve thousand”.
Pennsylvania and Virginia: ceilings
Pennsylvania, a $40,000 car first reported at 3,000 miles: 10 cents x 3,000 = $300; 10% of the price = $4,000; the lesser is at most $300.00 (73 P.S. 1955). Virginia, 9,000 miles to the first notice: half of 76 cents (the IRS business rate for 1 July to 31 December 2026) is 38 cents, so at most $3,420.00; at half of 72.5 cents (1 January to 30 June 2026) it is at most $3,262.50 (59.1-207.11). Virginia’s statute doesn’t say which date picks the rate.
Words-only states and Ohio
In Arizona, Illinois, Kansas, Missouri and Nebraska the statute gives no arithmetic, so the estimator shows the refund items total and no offset number. We don’t borrow another state’s divisor; whatever figure is used there is set by the maker, a program, a board or a court. Ohio’s statute has no deduction for use at all: with the example numbers, the refund items are $40,000 + $3,000 + $1,000 + $500 = $44,500.00 and the offset is $0.00 (ORC 1345.72(B)).
What the estimate leaves out
- Who decides. A maker’s offer, a program’s decision, a state board’s award or a court’s judgment sets the amount. Federal rules make a maker’s informal dispute program free to consumers and not binding on them (16 CFR 703.3(a), 703.5(j), eCFR up to date as of 9 Nov 2026); more in lemon law arbitration and maker programs.
- Damage allowances, caps and tax rules named in the state notes: Idaho’s 105% of MSRP cap, the proportional tax rules in Idaho and Minnesota, Texas’s $35 filing fee, California’s opt-in adjustments.
- Loan payoffs and who gets paid. Most of these statutes pay the refund to you and the lienholder “as their interests may appear”, so part of it may go straight to the lender.
- Replacement instead of refund. Some states let the consumer choose and some let the maker choose; several apply the same offset to a replacement (California, Missouri, Virginia). The state notes say which, where the text says.
- Leases in detail. Lease refunds split between you and the leasing company; see lemon laws for leased cars.
- Fees for a lawyer, damages beyond the refund, civil penalties and used-car rules. What each statute says about fees is on who pays lemon law attorney fees.
State rules in the estimator
Each state below was read in the statute’s official text on 11 November 2026, unless the note says otherwise. Tap a state for the refund items the statute lists, the details the estimator can’t apply, and the link to the official text. The full rules for each state (window, repair counts, notice, deadlines) are on lemon laws in all 50 states and DC.
| State | Offset | Miles counted | Section |
|---|---|---|---|
| Arizona | Words only, no formula | Use before the first written report, plus later use while not in the shop | 44-1263(A), (C)-(D) |
| California | Price x miles / 120,000 | Miles before the first repair visit for the problem | 1793.2(d)(2)(B)-(C) |
| Colorado | Price x miles / 100,000 | Miles before the first repair visit, plus later miles while not in the shop | 42-10-103(1), (4) |
| Delaware | At most price x miles / 100,000 | Miles before the first report of the defect | 5003(a), (c) |
| District of Columbia | At most 10 cents a mile over 12,000 | All miles of operation over the first 12,000 | 50-502(b) |
| Florida | Price x miles / 120,000 (RV 60,000) | Miles to the settlement or the arbitration hearing, whichever comes first | 681.102(19), 681.104(2)(a) |
| Idaho | At most price x miles / 120,000 | Miles to the arbitration hearing | 48-903(1), (8) |
| Illinois | Words only, no formula | Use before the first report, plus later use while not in the shop | 380/3(a), (c), (f) |
| Iowa | Price x miles / 120,000 | Miles to the 3rd repair, the 1st repair of a defect likely to cause death or serious injury, or the 20th day out of service, whichever comes first | 322G.2(1), (6), (18); 322G.4(2) |
| Kansas | Words only: an outside cost guide | Use before the first report, plus later use while not in the shop | 50-645(c) |
| Maryland | At most 15% of the price | No miles: a share of the price | 14-1502(c) |
| Massachusetts | Price x miles / 100,000 (motorcycle 25,000) | Miles before the maker accepts the car’s return | 7N1/2(3) |
| Michigan | Price x (miles to first report + miles over 25,000) / 100,000 | Miles before the first report, plus all miles over 25,000 | 257.1403(1)-(2) |
| Minnesota | At most the lesser of 10 cents a mile or 10% of the price | The ceiling counts every mile driven; the allowance itself counts use while the car’s use and market value were not substantially impaired | subd. 3(a), (h) |
| Missouri | Words only, no formula | The statute names no miles | 407.560(1), 407.567.1 |
| Montana | Price x miles / 100,000 | Miles before the maker accepts the car’s return | 61-4-501(1), (6); 61-4-503(2) |
| Nebraska | Words only, no formula | Use before the first report, plus later use while not in the shop | 60-2703 |
| New Jersey | Price x miles / 100,000 | Miles when the car is first presented for repair of the defect | 56:12-30, 56:12-32(a) |
| New York | (Miles – 12,000) x price / 100,000 | Total miles; the first 12,000 are free | 198-a(a)(4), (c)(1) |
| North Carolina | Price x miles / 120,000 | Miles to the 3rd repair of the defect or the 20th business day out of service, whichever comes first | 20-351.3(a), (c) |
| North Dakota | At most the lesser of 10 cents a mile or 10% of the price | Use before the first report, plus later use while not in the shop | 51-07-18(1) |
| Ohio | None: no deduction for use | No miles counted | 1345.72(B) |
| Oklahoma | (Miles over 15,000) x price / 120,000 | Consumer miles beyond the first 15,000 | 901(C) |
| Oregon | (Price + collateral charges) x miles / 120,000 (motorcycle 25,000, motor home 90,000) | Odometer when the maker acts, less 10 miles per period you didn’t have the car | 646A.400(1), 646A.404(1)(b), (3) |
| Pennsylvania | At most the lesser of 10 cents a mile or 10% of the price | Miles before the first report to the maker | sec. 5 (73 P.S. 1955) |
| Rhode Island | Price x miles / 100,000 | Miles before the first report, plus later miles while not in the shop | 31-5.2-3 |
| South Carolina | Price x miles / 120,000 | Miles before the first report of the defect | 56-28-40 |
| South Dakota | Price x miles / 100,000 | Miles before the first report of the defect | 32-6D-3, -4 |
| Texas | Total price (with taxes and fees) at full rate to first report + half rate to the hearing, / 120,000 | Miles to the first report at full rate, then first report to the hearing at half rate | 2301.604(a); 43 TAC 224.260 |
| Vermont | Price x miles / 100,000 | Miles before the first repair attempt | 4172(e) |
| Virginia | At most half the IRS business mileage rate a mile | Miles up to the first notice of the defect to the maker, its agents or a dealer | 59.1-207.11, -207.13(A) |
| Washington | Price x miles / 120,000 (motor home 90,000, motorcycle 25,000) | Miles before the first attempt to diagnose or repair the defect | 19.118.021, 19.118.041(1) |
Arizona: Words only, no formula
- Offset: Words only, no formula. Miles: Use before the first written report, plus later use while not in the shop (44-1263(A), (C)-(D)).
- Refund items in the statute: The full purchase price “including all collateral charges” (the article does not define them); the maker refunds “the amount of tax attributed to the sale” (44-1263(C)).
- Notes: The statute says only “reasonable allowance” and gives no formula, so the estimator shows no offset number. Leases are covered (44-1261(A)(1)).
- Official text: Ariz. Rev. Stat. 44-1263. Read 11 Nov 2026.
California: Price x miles / 120,000
- Offset: Price x miles / 120,000. Miles: Miles before the first repair visit for the problem (1793.2(d)(2)(B)-(C)).
- Refund items in the statute: The “actual price paid or payable” including transportation and maker-installed options but not non-maker items a dealer or the buyer installed, plus collateral charges such as sales or use tax, license, registration and other official fees, plus incidental damages such as repair, towing and rental (1793.2(d)(2)(B)). Finance charges are not named in that list, so the estimator leaves them out; whether they count as part of the price “paid or payable” is for the maker, a board or a court.
- Notes: The price is “paid or payable”, and the miles are those “traveled by the new motor vehicle” before the buyer “first delivered the vehicle” for correction of the problem (1793.2(d)(2)(C)). The same deduction applies to a replacement. For makers on the Department of Consumer Affairs opt-in list, CCP 871.27 adds adjustments the estimator does not make (third-party add-ons, negative equity, maker rebates); check DCA’s list for the brand.
- Official text: Cal. Civ. Code 1793.2. Read 11 Nov 2026. Civil Code 1793.2 as last amended by Stats. 2024 ch. 196.
Colorado: Price x miles / 100,000
- Offset: Price x miles / 100,000. Miles: Miles before the first repair visit, plus later miles while not in the shop (42-10-103(1), (4)).
- Refund items in the statute: The full purchase price, “including the sales tax, license fees, and registration fees and any similar governmental charges” (42-10-103(1)).
- Notes: The formula uses the “total contract price or lessee cost” (42-10-103(4), added by SB 24-192, effective 7 August 2024). The article excludes motor homes and vehicles on three or fewer wheels (42-10-101(2)). Who chooses refund or replacement: “at the manufacturer’s option”.
- Official text: Colo. Rev. Stat. 42-10-103 (CRS 2026, title 42 PDF). Read 11 Nov 2026. Colorado Revised Statutes 2026.
Delaware: At most price x miles / 100,000
- Offset: At most price x miles / 100,000. Miles: Miles before the first report of the defect (5003(a), (c)).
- Refund items in the statute: The full purchase price with trade-in credits, plus “related purchase costs, including sales taxes, registration fees and dealer preparation fees” (5003(a), (c)).
- Notes: The allowance is “not to exceed” the formula, so the estimate is a ceiling. A separate allowance for damage beyond normal wear may also come off (5003(c)(2)). The consumer may decline a replacement (5003(a)).
- Official text: 6 Del. C. ch. 50. Read 11 Nov 2026.
District of Columbia: At most 10 cents a mile over 12,000
- Offset: At most 10 cents a mile over 12,000. Miles: All miles of operation over the first 12,000 (50-502(b)).
- Refund items in the statute: The full purchase price “including all sales tax, license fees, registration fees, and any similar governmental charges” (50-502(b)).
- Notes: The allowance is “not to exceed 10 cents per mile” over the first 12,000 miles, plus an allowance for damage not from normal wear or the defect (50-502(b)). A claim goes first to the Board of Consumer Claims Arbitration (50-502(f)).
- Official text: D.C. Code 50-502. Read 11 Nov 2026.
Florida: Price x miles / 120,000 (RV 60,000)
- Offset: Price x miles / 120,000 (RV 60,000). Miles: Miles to the settlement or the arbitration hearing, whichever comes first (681.102(19), 681.104(2)(a)).
- Refund items in the statute: The purchase price (cash price with trade-in allowance) plus collateral charges (including maker- or agent-installed items, earned finance charges, sales taxes and title charges) and incidental charges caused by the defect (681.102, 681.104(2)(a)).
- Notes: The offset uses the “base selling or sale price … exclusive of taxes, government fees, and dealer fees” (for a lease, the agreed-upon value), so enter that figure as the price. Recreational vehicles divide by 60,000 (681.102(19)). The consumer has “an unconditional right to choose a refund”.
- Official text: Fla. Stat. ch. 681. Read 11 Nov 2026.
Idaho: At most price x miles / 120,000
- Offset: At most price x miles / 120,000. Miles: Miles to the arbitration hearing (48-903(1), (8)).
- Refund items in the statute: The amount paid with any trade-in, capped at 105% of the maker’s suggested retail price, plus “all other charges including” sales or excise tax, license and registration fees, towing and rental (48-903(1)).
- Notes: The allowance is “not to exceed” the formula, so the estimate is a ceiling. The 105% cap and the rule that cuts the tax refund in proportion to the allowance (48-903(8)) are not applied by the estimator.
- Official text: Idaho Code 48-903. Read 11 Nov 2026.
Illinois: Words only, no formula
- Offset: Words only, no formula. Miles: Use before the first report, plus later use while not in the shop (380/3(a), (c), (f)).
- Refund items in the statute: The full purchase price or lease cost “including all collateral charges”, but collateral charges do “not include taxes paid by the purchaser on the initial purchase” (380/3(a), (f)).
- Notes: The allowance is “that amount directly attributable to the wear and tear” from use before the first report and while not out of service (380/3(c)). No formula, so no offset number. The Act doesn’t say who chooses refund or replacement.
- Official text: 815 ILCS 380. Read 11 Nov 2026. Read from the legislature’s repository, updated 30 Oct 2026 with Public Acts through 104-854.
Iowa: Price x miles / 120,000
- Offset: Price x miles / 120,000. Miles: Miles to the 3rd repair, the 1st repair of a defect likely to cause death or serious injury, or the 20th day out of service, whichever comes first (322G.2(1), (6), (18); 322G.4(2)).
- Refund items in the statute: The full purchase or lease price plus “all collateral and reasonably incurred incidental charges” (322G.4(2)). Collateral charges include installed items, earned finance charges, use taxes and title charges; incidental charges include towing and alternative transportation (322G.2(1), (6)).
- Notes: Days are calendar days (322G.2(4)). For a lease the price is the lessor’s actual lease price plus 2% of the purchase price (322G.2(18)), which the estimator doesn’t compute, so leases show not confirmed. The consumer has “an unconditional right to choose a refund”.
- Official text: Iowa Code ch. 322G. Read 11 Nov 2026.
Kansas: Words only: an outside cost guide
- Offset: Words only: an outside cost guide. Miles: Use before the first report, plus later use while not in the shop (50-645(c)).
- Refund items in the statute: The full purchase or lease price “including all collateral charges” (50-645(c)); the section does not list them.
- Notes: The allowance is “calculated from the most recent edition of Your Driving Costs, published by the American automobile association” (50-645(c)). That is a private publication, not a number in the statute, so the estimator shows no offset number.
- Official text: Kan. Stat. 50-645. Read 11 Nov 2026.
Maryland: At most 15% of the price
- Offset: At most 15% of the price. Miles: No miles: a share of the price (14-1502(c)).
- Refund items in the statute: The full purchase price “including all license fees, registration fees, and any similar governmental charges” (14-1502(c)).
- Notes: The allowance is “not to exceed 15 percent of the purchase price”, plus an allowance for damage not from normal wear (14-1502(c)). Sales tax is not named; the section doesn’t say whether it counts as a “similar governmental charge”, and the estimator adds the taxes and fees you enter. The consumer chooses. A fleet purchase of five or more vehicles is outside the subtitle (14-1502(m)).
- Official text: Md. Com. Law 14-1502. Read 11 Nov 2026.
Massachusetts: Price x miles / 100,000 (motorcycle 25,000)
- Offset: Price x miles / 100,000 (motorcycle 25,000). Miles: Miles before the maker accepts the car’s return (7N1/2(3)).
- Refund items in the statute: The full contract price with trade-in credits, plus sales tax, registration fee, finance charges and dealer-added options, plus towing and reasonable rental costs when these weren’t provided free (7N1/2(3)).
- Notes: For a lease, the price in the formula is “the total amount of payments made”. Motorcycles divide by 25,000. Miles you drive while keeping the car after its return is accepted add to the count. Any cash award the consumer accepted from the maker also comes off. The consumer has an “unqualified right” to reject a replacement.
- Official text: Mass. Gen. Laws c. 90 s. 7N1/2. Read 11 Nov 2026.
Michigan: Price x (miles to first report + miles over 25,000) / 100,000
- Offset: Price x (miles to first report + miles over 25,000) / 100,000. Miles: Miles before the first report, plus all miles over 25,000 (257.1403(1)-(2)).
- Refund items in the statute: The purchase or lease price, which includes options and “all other charges made by or for the manufacturer”, plus towing and comparable rental costs if these weren’t provided free (257.1403(2)). Taxes and finance charges are not named, so the estimator leaves them out.
- Notes: Appraised damage not from normal use or the defect also comes off (257.1403(2)). A court or the maker’s program may reduce the part for miles over 25,000 if the car did not give reliable transportation in that period (257.1403(3)). The consumer “shall have the right to demand a refund” (257.1403(1)(a)).
- Official text: MCL 257.1401-.1410. Read 11 Nov 2026. Michigan Compiled Laws, complete through PA 114 of 2026.
Minnesota: At most the lesser of 10 cents a mile or 10% of the price
- Offset: At most the lesser of 10 cents a mile or 10% of the price. Miles: the ceiling is per “mile driven”; the allowance is the amount “directly attributable to use by the consumer and any previous consumer during any period in which the use and market value of the motor vehicle are not substantially impaired” (subd. 3(a), (h)). The estimator applies the ceiling to all the miles you enter.
- Refund items in the statute: The full purchase price with options the maker or dealer added within 30 days of delivery, sales or excise tax, license and registration fees, and towing and rental costs from warranty repairs (subd. 3(a)).
- Notes: The allowance is “not exceeding ten cents per mile driven or ten percent of the purchase price, whichever is less”. The tax refund is cut in proportion to the allowance (subd. 3(h)), which the estimator doesn’t apply. A lessee gets a refund only, not a replacement (subd. 4).
- Official text: Minn. Stat. 325F.665. Read 11 Nov 2026.
Missouri: Words only, no formula
- Offset: Words only, no formula. Miles: The statute names no miles (407.560(1), 407.567.1).
- Refund items in the statute: The full purchase price “including all reasonably incurred collateral charges”: charges not on the maker’s price label, such as sales tax, license, registration and title fees and inspections (407.567.1, 407.560(1)).
- Notes: The statute says only “a reasonable allowance for the consumer’s use” and applies it to a replacement too. No number is shown. The maker chooses (“at its option”).
- Official text: Mo. Rev. Stat. 407.560-.579. Read 11 Nov 2026.
Montana: Price x miles / 100,000
- Offset: Price x miles / 100,000. Miles: Miles before the maker accepts the car’s return (61-4-501(1), (6); 61-4-503(2)).
- Refund items in the statute: The full purchase price “plus reasonable collateral charges and incidental damages” (61-4-503(2)); collateral charges are governmental charges such as sales and property tax and license and registration fees (61-4-501(1)).
- Notes: The definition first speaks of use before the first written notice and while not out of service, then says the allowance “must be computed” on miles before the maker’s acceptance of return (61-4-501(6)); the estimator uses the computing sentence.
- Official text: Mont. Code 61-4-501 to -533. Read 11 Nov 2026. Montana Code Annotated 2025.
Nebraska: Words only, no formula
- Offset: Words only, no formula. Miles: Use before the first report, plus later use while not in the shop (60-2703).
- Refund items in the statute: The full purchase price “including all sales taxes, license fees, and registration fees and any similar governmental charges” (60-2703).
- Notes: The allowance is the amount “directly attributable to use by the consumer and any previous owner” before the first report and while not out of service. No number is shown.
- Official text: Neb. Rev. Stat. 60-2703. Read 11 Nov 2026.
New Jersey: Price x miles / 100,000
- Offset: Price x miles / 100,000. Miles: Miles when the car is first presented for repair of the defect (56:12-30, 56:12-32(a)).
- Refund items in the statute: The purchase price with trade-in credit, options the maker or dealer added within 30 days, sales tax, license and registration fees, finance charges, towing and rental (56:12-32(a)).
- Notes: The offset uses the purchase price “or the lease price if applicable”. The consumer may reject a replacement and demand a refund. Used cars under 56:8-71 follow a different deduction (the IRS business rate on the repurchase date), not in this estimator.
- Official text: N.J.S.A. 56:12-29 et seq.. Read 11 Nov 2026.
New York: (Miles – 12,000) x price / 100,000
- Offset: (Miles – 12,000) x price / 100,000. Miles: Total miles; the first 12,000 are free (198-a(a)(4), (c)(1)).
- Refund items in the statute: The full purchase price or lease price with any trade-in allowance, plus license, registration and similar governmental fees (198-a(c)(1)). Sales tax comes back from the commissioner of taxation and finance on application, not from the maker (198-a(c)(2)). The estimator still adds the taxes and fees you enter and says so.
- Notes: The statute does not say on which date the miles are counted. A separate allowance for damage beyond normal wear may also come off. Motor homes use the same formula (198-a(n)(5)). Used cars under 198-b have no mileage deduction.
- Official text: N.Y. Gen. Bus. Law 198-a. Read 11 Nov 2026.
North Carolina: Price x miles / 120,000
- Offset: Price x miles / 120,000. Miles: Miles to the 3rd repair of the defect or the 20th business day out of service, whichever comes first (20-351.3(a), (c)).
- Refund items in the statute: The full contract price with options and non-refundable service-contract portions, collateral charges such as sales tax, license and registration fees, finance charges incurred after the first report, and incidental and consequential damages (20-351.3(a)).
- Notes: For a lease, the formula uses “the lessor’s actual lease price”. Enter only finance charges from after the first report. The consumer chooses refund or replacement.
- Official text: N.C. Gen. Stat. 20-351 to -351.11. Read 11 Nov 2026.
North Dakota: At most the lesser of 10 cents a mile or 10% of the price
- Offset: At most the lesser of 10 cents a mile or 10% of the price. Miles: Use before the first report, plus later use while not in the shop (51-07-18(1)).
- Refund items in the statute: The full purchase price “including all collateral charges” (51-07-18(1)); the sections we read don’t list them, so the estimator counts the price only.
- Notes: The allowance is “not exceeding ten cents per mile … driven or ten percent of the purchase price, whichever is less”. House cars are outside the definition (51-07-16(2)).
- Official text: N.D. Cent. Code 51-07-16 to -22. Read 11 Nov 2026.
Ohio: None: no deduction for use
- Offset: None: no deduction for use. Miles: No miles counted (1345.72(B)).
- Refund items in the statute: The full purchase price (including finance charges, credit insurance, service contracts, taxes and fees, per 1345.71) plus incidental damages such as towing, rental, meals, lodging and loan or lease fees (1345.72(B)).
- Notes: We read 1345.71 to 1345.78 in full: no section allows a deduction for use, so the offset is $0 by statute.
- Official text: Ohio Rev. Code 1345.72. Read 11 Nov 2026.
Oklahoma: (Miles over 15,000) x price / 120,000
- Offset: (Miles over 15,000) x price / 120,000. Miles: Consumer miles beyond the first 15,000 (901(C)).
- Refund items in the statute: The full purchase price “including all taxes, license, registration fees and all similar governmental fees, excluding interest” (901(C)).
- Notes: The formula uses the “purchase or lease price”. Read in the enrolled 2022 act (effective 1 Nov 2022); later amendments were not checked.
- Official text: 15 O.S. 901 (enrolled HB 3217, 2022). Read 11 Nov 2026. Enrolled HB 3217 (2022).
Oregon: (Price + collateral charges) x miles / 120,000 (motorcycle 25,000, motor home 90,000)
- Offset: (Price + collateral charges) x miles / 120,000 (motorcycle 25,000, motor home 90,000). Miles: Odometer when the maker acts, less 10 miles per period you didn’t have the car (646A.400(1), 646A.404(1)(b), (3)).
- Refund items in the statute: The full purchase or lease price and collateral charges paid: taxes, license, registration and title fees, finance charges, prepayment penalties, undercoating and installed options, and aftermarket items bought within 20 days (646A.400(1), 646A.404(1)(b)).
- Notes: Oregon multiplies the cash or lease price plus collateral charges, so the estimator adds your taxes, fees and finance charges to the price for the offset. The miles are the vehicle’s mileage when the maker acts, less “10 miles for mileage that the motor vehicle traveled during any period” you didn’t have it while it was being repaired (646A.404(3)(b)); the estimator reads that as 10 miles per period.
- Official text: Or. Rev. Stat. 646A.400-.418. Read 11 Nov 2026.
Pennsylvania: At most the lesser of 10 cents a mile or 10% of the price
- Offset: At most the lesser of 10 cents a mile or 10% of the price. Miles: Miles before the first report to the maker (sec. 5 (73 P.S. 1955)).
- Refund items in the statute: The full purchase or lease price “including all collateral charges” (sec. 5); the estimator counts the price only and leaves collateral charges to the statute’s text.
- Notes: The allowance is “not exceeding 10¢ per mile driven or 10% of the purchase price or lease price …, whichever is less”, for use “prior to his first report”. The definition of a new motor vehicle includes motorcycles (added by Act 151 of 2024) and leaves out motor homes. The purchaser chooses.
- Official text: 73 P.S. 1951-1963 (Act 28 of 1984). Read 11 Nov 2026.
Rhode Island: Price x miles / 100,000
- Offset: Price x miles / 100,000. Miles: Miles before the first report, plus later miles while not in the shop (31-5.2-3).
- Refund items in the statute: The full contract or lease price with trade-in credits, plus incidental costs including sales tax, registration fee, finance charges and dealer-added options, plus towing and rental when not provided free (31-5.2-3).
- Notes: The formula uses the “total contract price or lessee cost”. The consumer or lessee chooses refund or replacement.
- Official text: R.I. Gen. Laws 31-5.2-3. Read 11 Nov 2026.
South Carolina: Price x miles / 120,000
- Offset: Price x miles / 120,000. Miles: Miles before the first report of the defect (56-28-40).
- Refund items in the statute: The full purchase price “as delivered including applicable finance charges, sales taxes, license fees, registration fees, and any other similar governmental charges” (56-28-40).
- Notes: The maker may choose to replace (“at its option”).
- Official text: S.C. Code 56-28-10 to -110. Read 11 Nov 2026.
South Dakota: Price x miles / 100,000
- Offset: Price x miles / 100,000. Miles: Miles before the first report of the defect (32-6D-3, -4).
- Refund items in the statute: The full contract price with undercoating, dealer preparation, transportation and installed options and non-refundable extended-warranty portions; collateral charges such as excise tax, license and registration fees; finance charges after the first report; and alternative transportation costs (32-6D-3).
- Notes: Enter only finance charges from after the first report. The consumer chooses refund or replacement.
- Official text: S.D. Codified Laws ch. 32-6D. Read 11 Nov 2026.
Texas: Total price at full rate to first report + half rate to the hearing, / 120,000
- Offset: Total purchase price at full rate to first report + half rate to the hearing, / 120,000. Miles: Miles to the first report at full rate, then first report to the hearing at half rate (2301.604(a); 43 TAC 224.260).
- Refund items in the statute: The “total purchase price … excluding the amount of any interest, finance charge, or insurance premiums” (43 TAC 224.260), plus reasonable incidental costs (2301.604(a); 43 TAC 224.262), and the refund includes the $35 filing fee (2301.712; 43 TAC 224.260); the estimator doesn’t add the fee.
- Notes: The offset multiplies the same total purchase price. TxDMV’s own repurchase worksheet shows that price including tax, title, license and registration, so the estimator uses your price plus taxes and fees for Texas. The 120,000-mile useful life is a rebuttable presumption in the rule. Towable recreational vehicles use days (5,475) instead of miles; the estimator doesn’t compute them.
- Official text: Tex. Occ. Code 2301.601-.613; 43 TAC 224.260. Read 11 Nov 2026. Texas statutes current through the 89th Legislature, 2nd Called Session, 2025.
Vermont: Price x miles / 100,000
- Offset: Price x miles / 100,000. Miles: Miles before the first repair attempt (4172(e)).
- Refund items in the statute: The full purchase price with trade-in or down payment, finance charges, credit charges, registration fees and similar charges, and incidental and consequential damages (4172(e)). Vermont purchase and use tax comes back from the State in proportion, on a claim filed within 90 days of the order (4172(e)); the estimator still adds the taxes and fees you enter and says so.
- Notes: The consumer chooses refund or replacement.
- Official text: 9 V.S.A. 4172. Read 11 Nov 2026.
Virginia: At most half the IRS business mileage rate a mile
- Offset: At most half the IRS business mileage rate a mile. Miles: Miles up to the first notice of the defect to the maker, its agents or a dealer (59.1-207.11, -207.13(A)).
- Refund items in the statute: The full contract price, collateral charges (sales tax, license, registration and title fees, finance charges and interest, transportation, dealer preparation, service contracts, undercoating, rust proofing, installed options) and incidental damages (59.1-207.13(A)).
- Notes: The allowance “shall not exceed one-half” of the IRS business mileage rate, plus damage beyond normal wear (59.1-207.11). The statute names no date for choosing the rate, so the estimator lets you pick the period and shows the rate used. The consumer has “the unconditional right to choose a refund”.
- Official text: Va. Code 59.1-207.9 to -207.16:1. Read 11 Nov 2026.
Washington: Price x miles / 120,000 (motor home 90,000, motorcycle 25,000)
- Offset: Price x miles / 120,000 (motor home 90,000, motorcycle 25,000). Miles: Miles before the first attempt to diagnose or repair the defect (19.118.021, 19.118.041(1)).
- Refund items in the statute: The purchase price (cash price with trade-in, less maker rebates), collateral charges (sales tax, license, registration and title fees, finance charges, transportation, dealer preparation, service contracts, options and more) and incidental costs such as towing (19.118.041(1), 19.118.021).
- Notes: For a claim based only on days out of service, miles count only to the 15th cumulative day out of service (motor homes: the 30th). For a motor home the board may raise or lower the offset by up to a third. Later owners who choose a repurchase count only their own miles (19.118.041(1)(c)). Leases refund payments made, but the offset text names the purchase price, so leases show not confirmed in the estimator.
- Official text: Rev. Code Wash. ch. 19.118. Read 11 Nov 2026.
States not in the estimator
The other 19 states are left out, for one of three reasons, and the tool shows “not confirmed” for them:
- Statute not confirmed in current official text: Arkansas, Mississippi, New Hampshire, Tennessee and Wisconsin. Georgia (the official text the Attorney General posts runs through the 2024 session, and a 2025 bill reworded the very definition the offset sits in) and Indiana (we could open only an archived copy, dated 3 August 2026, of the official 2026 code file).
- Offset read, but not yet the refund wording in full: Alabama, Connecticut, Hawaii and Utah (Utah’s formula is in a Division rule, R152-20-202, in force 19 August 2026, not in the statute). We read their offset rules; the estimator adds them once their refund lists are read as well.
- No formula, and the refund wording not read for this tool: Alaska, Kentucky, Louisiana, Maine, Nevada, New Mexico, West Virginia and Wyoming. Most say “reasonable allowance” without arithmetic; Maine and Alaska set ceilings in words that need the full section to apply; West Virginia leaves the remedy to the court.
For any of these, the all-states page linked above gives the state agency and the official code.
What to gather next
Whatever the estimate says, the figures that matter come from your paperwork, so keep it together and in order:
- The purchase or lease contract: cash price, trade-in credit, rebates, taxes and each fee on its own line.
- Every repair order, with the date in and out, the odometer reading and the complaint as written. The first one for this defect often sets the miles your state counts.
- Any written notice you sent the maker, with proof of how it was sent, and anything the maker sent back.
- Loan statements showing finance charges paid, and receipts for towing, rental and other costs caused by the defect.
- The steps your state puts before a refund (written notice, a maker program, a state board), which the deadline rule lookup lists in words with each section.
Fact-check note: statutes and rules checked on 11 November 2026. IRS rates from the IRS standard mileage rates page (last updated 28 July 2026; IR-2024-312, IR-2025-128 and IR-2026-29), rechecked each January and July. State rows are rechecked every three months and after each state’s legislative session. Spot an error? Tell us through our corrections page.
Formulas and sources
- Rule type for this state before the vehicle and lease checks: State statutes in the table on this page, read 11 Nov 2026
- Vehicle type read for this state (1 yes, 0 no): State statutes in the table on this page, read 11 Nov 2026
- Lease read for this state (1 yes, 0 no): State statutes in the table on this page, read 11 Nov 2026
- Rule type used: State statutes in the table on this page, read 11 Nov 2026
- Divisor for a car in this state: State statutes in the table on this page, read 11 Nov 2026
- Divisor used: State statutes in the table on this page, read 11 Nov 2026
- Miles basis code: State statutes in the table on this page, read 11 Nov 2026
- Refund items code: State statutes in the table on this page, read 11 Nov 2026
- Refund items code shown: State statutes in the table on this page, read 11 Nov 2026
- Miles from delivery to the first point: Arithmetic on the reader's own entries, no outside figure
- Miles from delivery to the later point: Arithmetic on the reader's own entries, no outside figure
- Miles the basis picks: Arithmetic on the reader's own entries, no outside figure
- IRS business rate used (dollars a mile): IRS standard mileage rates (IR-2025-128; IR-2026-29), page updated 28 Jul 2026
- Refund items total: State statutes in the table on this page, read 11 Nov 2026
- Miles counted in the estimate: State statutes in the table on this page, read 11 Nov 2026
- Texas miles at half rate: State statutes in the table on this page, read 11 Nov 2026
- Use offset estimate: State statutes in the table on this page, read 11 Nov 2026
- Refund items minus the offset: State statutes in the table on this page, read 11 Nov 2026
- How the offset is shown: State statutes in the table on this page, read 11 Nov 2026
- Divisor shown: State statutes in the table on this page, read 11 Nov 2026
- IRS rate shown in cents (Virginia): State statutes in the table on this page, read 11 Nov 2026
- Statute section shown: State statutes in the table on this page, read 11 Nov 2026
- IRS business mileage rate, 2025 (dollars a mile) (0.7, as of 2026-11-11): IRS standard mileage rates (IR-2024-312), page updated 28 Jul 2026
- IRS business mileage rate, 1 Jan to 30 Jun 2026 (dollars a mile) (0.725, as of 2026-11-11): IRS standard mileage rates (IR-2025-128; IR-2026-29), page updated 28 Jul 2026
- IRS business mileage rate, 1 Jul to 31 Dec 2026 (dollars a mile) (0.76, as of 2026-11-11): IRS standard mileage rates (IR-2025-128; IR-2026-29), page updated 28 Jul 2026
Sources
- Ariz. Rev. Stat. 44-1263, 44-1263(A), (C)-(D) (official text, read 11 Nov 2026)
- Cal. Civ. Code 1793.2, 1793.2(d)(2)(B)-(C) (official text, read 11 Nov 2026; Civil Code 1793.2 as last amended by Stats. 2024 ch. 196)
- Colo. Rev. Stat. 42-10-103 (CRS 2026, title 42 PDF), 42-10-103(1), (4) (official text, read 11 Nov 2026; Colorado Revised Statutes 2026)
- 6 Del. C. ch. 50, 5003(a), (c) (official text, read 11 Nov 2026)
- D.C. Code 50-502, 50-502(b) (official text, read 11 Nov 2026)
- Fla. Stat. ch. 681, 681.102(19), 681.104(2)(a) (official text, read 11 Nov 2026)
- Idaho Code 48-903, 48-903(1), (8) (official text, read 11 Nov 2026)
- 815 ILCS 380, 380/3(a), (c), (f) (official text, read 11 Nov 2026; Read from the legislature's repository, updated 30 Oct 2026 with Public Acts through 104-854)
- Iowa Code ch. 322G, 322G.2(1), (6), (18); 322G.4(2) (official text, read 11 Nov 2026)
- Kan. Stat. 50-645, 50-645(c) (official text, read 11 Nov 2026)
- Md. Com. Law 14-1502, 14-1502(c) (official text, read 11 Nov 2026)
- Mass. Gen. Laws c. 90 s. 7N1/2, 7N1/2(3) (official text, read 11 Nov 2026)
- MCL 257.1401-.1410, 257.1403(1)-(2) (official text, read 11 Nov 2026; Michigan Compiled Laws, complete through PA 114 of 2026)
- Minn. Stat. 325F.665, subd. 3(a), (h) (official text, read 11 Nov 2026)
- Mo. Rev. Stat. 407.560-.579, 407.560(1), 407.567.1 (official text, read 11 Nov 2026)
- Mont. Code 61-4-501 to -533, 61-4-501(1), (6); 61-4-503(2) (official text, read 11 Nov 2026; Montana Code Annotated 2025)
- Neb. Rev. Stat. 60-2703, 60-2703 (official text, read 11 Nov 2026)
- N.J.S.A. 56:12-29 et seq., 56:12-30, 56:12-32(a) (official text, read 11 Nov 2026)
- N.Y. Gen. Bus. Law 198-a, 198-a(a)(4), (c)(1) (official text, read 11 Nov 2026)
- N.C. Gen. Stat. 20-351 to -351.11, 20-351.3(a), (c) (official text, read 11 Nov 2026)
- N.D. Cent. Code 51-07-16 to -22, 51-07-18(1) (official text, read 11 Nov 2026)
- Ohio Rev. Code 1345.72, 1345.72(B) (official text, read 11 Nov 2026)
- 15 O.S. 901 (enrolled HB 3217, 2022), 901(C) (official text, read 11 Nov 2026; Enrolled HB 3217 (2022))
- Or. Rev. Stat. 646A.400-.418, 646A.400(1), 646A.404(1)(b), (3) (official text, read 11 Nov 2026)
- 73 P.S. 1951-1963 (Act 28 of 1984), sec. 5 (73 P.S. 1955) (official text, read 11 Nov 2026)
- R.I. Gen. Laws 31-5.2-3, 31-5.2-3 (official text, read 11 Nov 2026)
- S.C. Code 56-28-10 to -110, 56-28-40 (official text, read 11 Nov 2026)
- S.D. Codified Laws ch. 32-6D, 32-6D-3, -4 (official text, read 11 Nov 2026)
- Tex. Occ. Code 2301.601-.613, 2301.712; 43 TAC 224.260, 224.262 (official text, read 11 Nov 2026; Texas statutes current through the 89th Legislature, 2nd Called Session, 2025)
- 9 V.S.A. 4172, 4172(e) (official text, read 11 Nov 2026)
- Va. Code 59.1-207.9 to -207.16:1, 59.1-207.11, -207.13(A) (official text, read 11 Nov 2026)
- Rev. Code Wash. ch. 19.118, 19.118.021, 19.118.041(1) (official text, read 11 Nov 2026)
- California Department of Consumer Affairs: manufacturers that opted in under CCP 871.29 (read 11 Nov 2026)
- IRS: Standard mileage rates (page updated 28 Jul 2026; read 11 Nov 2026)
- eCFR: 16 CFR part 703 (up to date as of 9 Nov 2026; read 11 Nov 2026)